Home Equity Line of Credit Without Tax Returns
Tap your home equity using bank statements or assets, and keep the low rate on your first mortgage.
- 30+ years of experience
- No tax returns
- Keep your first mortgage
What Is a No Tax Return HELOC?
A home equity line of credit (HELOC) is a second mortgage that works like a credit card secured by your home. You draw what you need and pay interest only on what you use.
Our no-tax-return versions qualify you with bank statements, a profit and loss statement, or your assets, which is ideal for self-employed homeowners.
Why Choose a No Tax Return HELOC?
Flexible access to your equity, without touching your first mortgage.
Keep Your Low Rate
Your first mortgage stays untouched.
No Tax Returns
Qualify with bank statements, a P&L, or assets.
Draw as Needed
Borrow, repay, and borrow again during the draw period.
Pay on What You Use
Interest is charged only on your outstanding balance.
Use It for Anything
Remodels, debt payoff, tuition, or your next investment.
Rentals Welcome
Some programs allow HELOCs on investment properties.
Do You Qualify?
If you’ve built equity, you may already qualify. Lenders look for:
- Equity in your home, often at least 15% to 20%
- Credit score of about 660 or higher
- Proof of income through bank statements, P&L, or assets
- A history of on-time mortgage payments
- An appraisal or valuation of your home
See How Much Equity You Can Access
Get a free estimate based on your home’s value and your current mortgage balance.
Prefer email? Send us a messageHELOC Questions
How much can I borrow?
Most programs let your first mortgage plus the HELOC reach 80% to 90% of your home’s value, depending on credit and property type.
How do I qualify without tax returns?
With 12 or 24 months of bank statements, a profit and loss statement, or documented assets, similar to our bank statement loans.
Why not do a cash-out refinance?
If your first mortgage has a low rate, a HELOC lets you keep it and borrow only what you need. A cash-out refinance replaces your whole loan.
Is the rate fixed or variable?
Most HELOC rates are variable. Some programs let you lock a fixed rate on part of your balance.
Can I get a HELOC on a rental property?
Yes, some programs allow it. Terms are usually a bit more conservative than on your primary home.
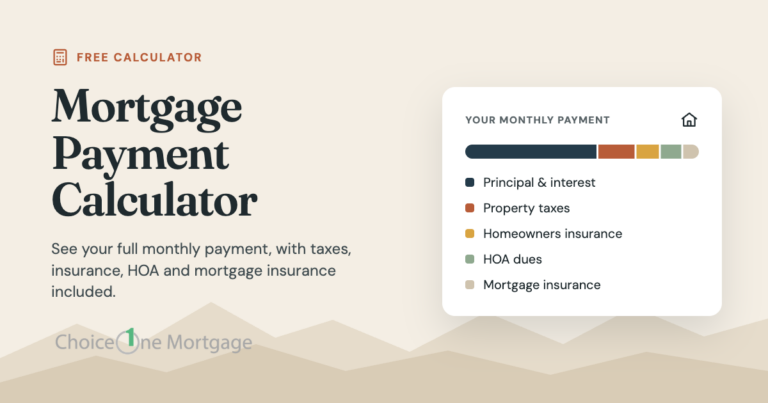
Run the Numbers First
Compare a refinance with keeping your current loan, and estimate new payments.

Access Your Equity in 3 Simple Steps
Tell Us Your Goals
Share your home value, balance, and how much you need.
We Find the Best Fit
We compare HELOC and refinance options for you.
Draw Your Funds
Use your line of credit whenever you need it.