Bank Statement Mortgages for Self-Employed Borrowers
Qualify with your real cash flow, not the income left after write-offs. No tax returns required.
- 30+ years of experience
- No tax returns
- Personal or business statements

What Is a Bank Statement Loan?
A bank statement loan uses the deposits in your bank accounts to show your income, instead of your tax returns.
It’s built for business owners and freelancers whose tax returns show less income because of legitimate business deductions.
Why Choose a Bank Statement Loan?
Keep your write-offs and still qualify for the home you can afford.
No Tax Returns
Your deposits tell the story, not your adjusted gross income.
Personal or Business
Use personal or business accounts, whichever shows your income best.
Built for Owners
Designed for business owners, contractors, freelancers, and gig workers.
Higher Loan Amounts
Financing for Southern California prices, including jumbo amounts.
Buy or Invest
Primary homes, second homes, and rental properties all qualify.
Purchase or Refinance
Buy a new home or refinance, including cash out.
Do You Qualify?
If you’ve run your business for a couple of years, you may already qualify. Lenders look for:
- Two years of self-employment
- 12 or 24 months of bank statements
- Credit score of about 620 or higher
- Down payment of 10% or more
- Cash reserves after closing
Find Out What You Qualify For
Get a free pre-approval, often the same day. No obligation.
Prefer email? Send us a messageBank Statement Loan Questions
How is my income calculated?
We average your deposits over 12 or 24 months. For business accounts, an expense factor or a profit and loss statement is used to estimate your business costs.
Should I use personal or business statements?
Whichever shows your income more clearly. Business owners who pay themselves irregularly often do better with business statements.
Are rates higher than a conventional loan?
Usually a bit higher, because these are non-QM loans. A strong credit score and larger down payment help narrow the gap.
Can I refinance later?
Yes. Many borrowers refinance into a conventional loan once their tax returns show enough income.
What other options do self-employed borrowers have?
See our self-employed mortgage options, including 1099, profit and loss, and asset-based programs.
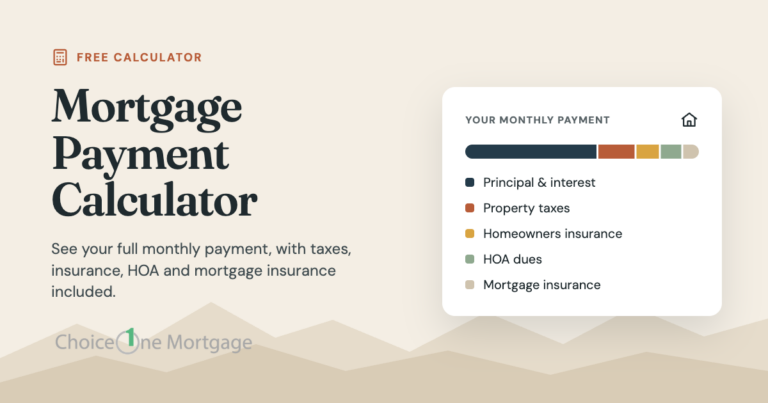
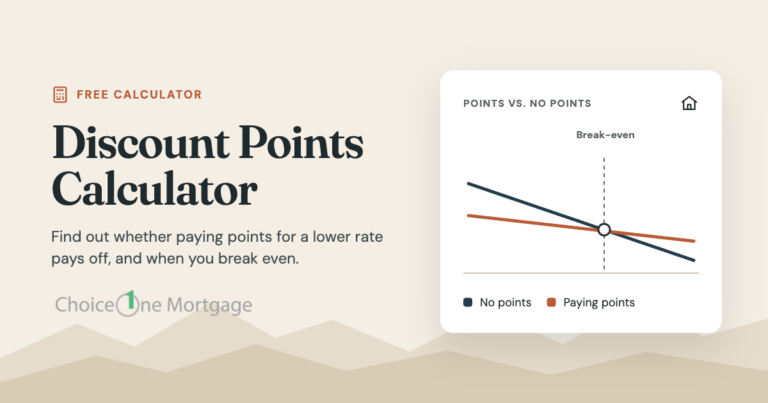
Run the Numbers First
See what you can afford and what your payment would be.

Get Pre-Approved in 3 Simple Steps
Tell Us Your Goals
Apply online in minutes or give us a call.
We Compare Your Options
We review your finances and find the best loan for you.
Get Your Pre-Approval
Shop for homes and make offers with confidence.